
IBM combines four Granite time-series models in a single ensemble recipe
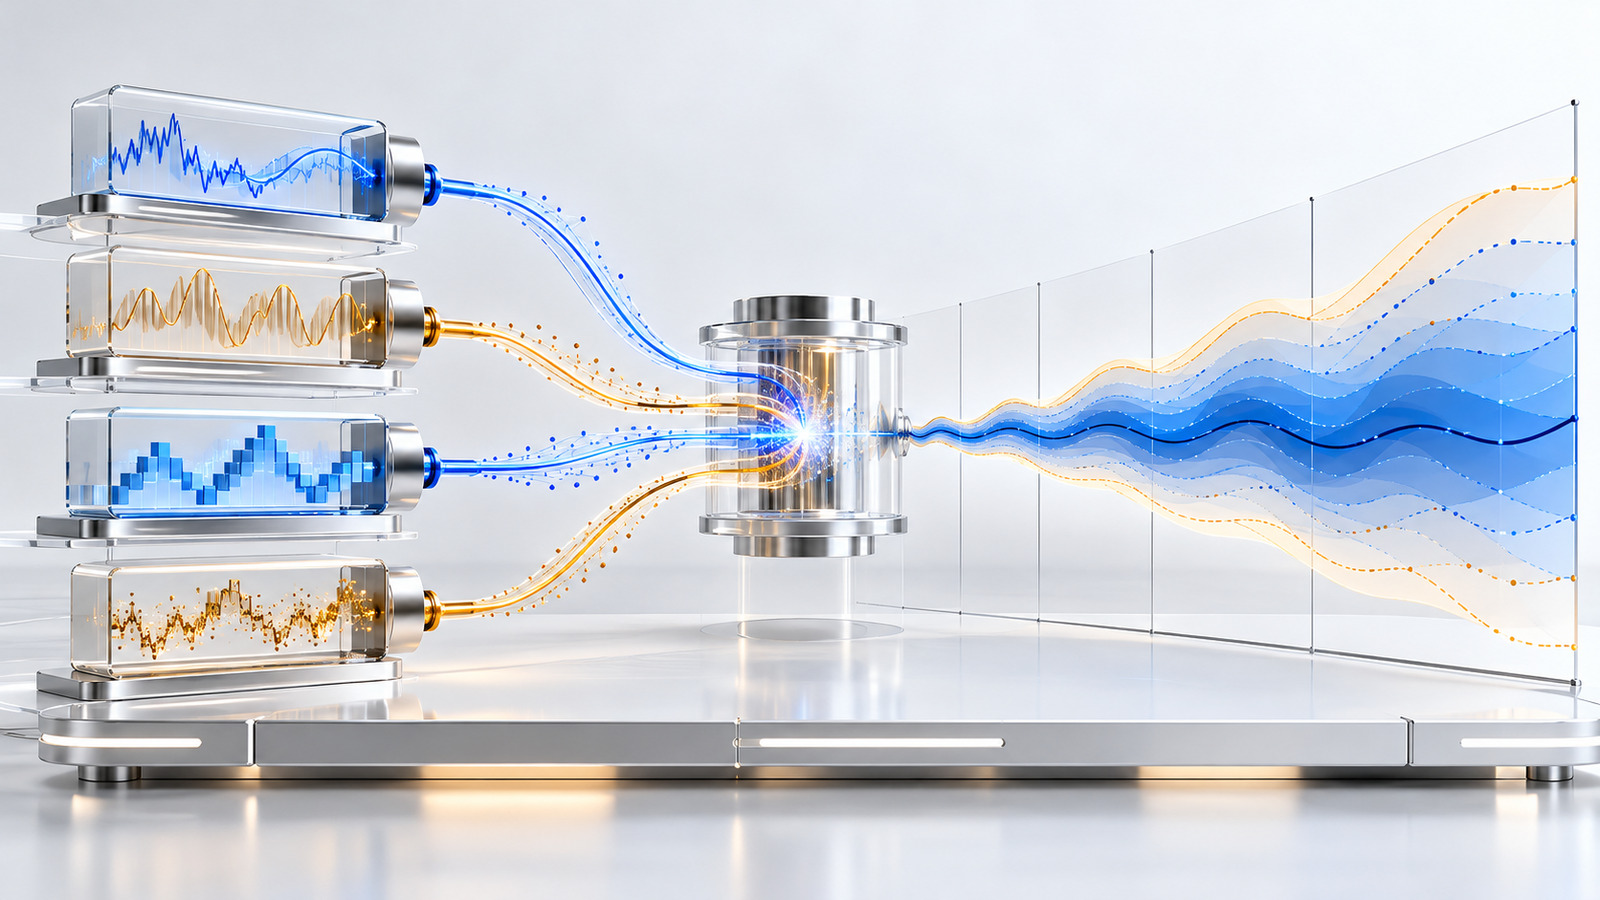
Granite Timeseries Ensemble R1 combines quantile forecasts from four open Granite forecasting models without retraining or distributing merged weights.
AT A GLANCE
Key points
- Four Granite models share a common quantile-forecasting interface
- The default recipe uses equal-weight pooling without retraining
- An alternative IQR method weights members by forecast dispersion
- The recipe is Apache-2.0, while member-model licenses still apply
What is changing?
IBM Research has detailed Granite Timeseries Ensemble R1, a recipe that combines forecasts from four complementary Granite time-series models. The default configuration downloads PatchTST-FM-r1, PatchTST-FM-r2, FlowState-r1.1, and TTM-r3 from their separate repositories at runtime. The release therefore provides a reusable ensemble framework rather than a new set of merged weights.
The recommended default uses uniform probability pooling, giving each model’s quantile forecasts equal influence. An alternative IQR-weighted method gives more weight to members with narrower forecast intervals. IBM cautions that narrower intervals do not by themselves indicate better accuracy and says both methods should be evaluated on representative application data.
In the Granite-only evaluation, both ensembles outperformed the collection’s strongest individual member on aggregate MASE. Loading four checkpoints, however, increases latency and memory use, while neither method guarantees calibration or robustness under distribution shift.
Explore the original sources
Source date: 22 October 2026.
Published by AI Radar: 22 Oct 2026, 12:00 (Istanbul, UTC+3).
FOLLOW THE TOPIC
Topics and tags
Share your discovery.
Send this story to a friend.
Reader comments
What do you think about this development? Share your experience or question. Comments are published after editorial approval.
Your name/nickname and comment become public if approved. Read: Privacy notice.



Loading comments…